DuitNow QR platform
PeGePay is a multi-channel DuitNow QR ecosystem that makes payment collection fast, easy and reliable for businesses of every size, from a single outlet to hundreds.
What we do
PeGePay is a multi-channel DuitNow QR ecosystem that makes payment collection fast, easy and reliable for businesses. We complement the banks' existing channels rather than replacing them.
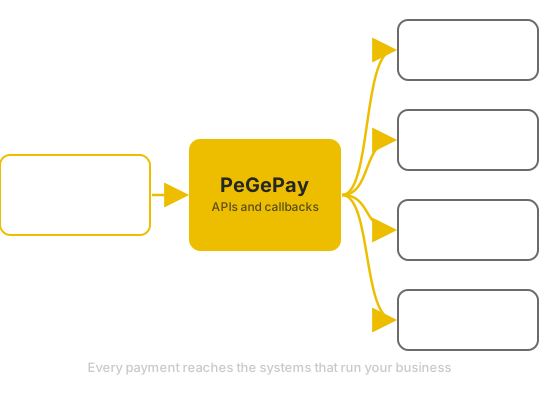
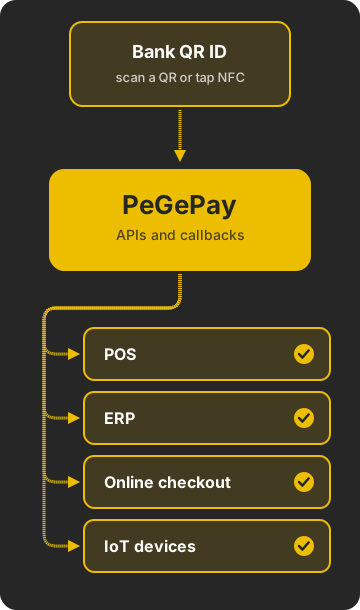
Every payment reaches the systems that run your business.
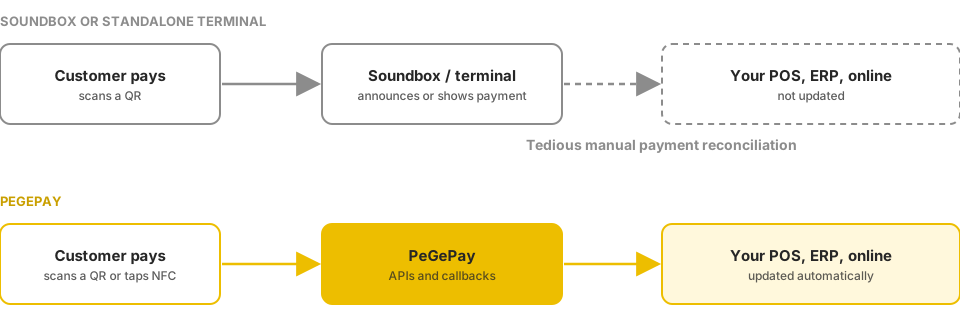
Soundboxes and low-cost payment terminals confirm that money arrived, but they are not integrated with your systems, so reconciliation stays manual. PeGePay passes every payment to your POS, enterprise systems, online channels and IoT devices, and reconciles by store, terminal and shift.
Turnkey integration with a bank's DuitNow APIs has been a project only the largest companies could afford in cost, speed and effectiveness. We have already done the integration with the banks. A merchant needs only the QR ID assigned by their bank, and setup and verification take about two minutes. Integrations survive a change of bank.
One platform for almost every online and storefront collection need: virtual static QR, POS, embedded QR, QR online checkout, NFC tap-to-pay, messaging commerce bots and APIs. Each is built to suit the specific needs of the business using it, from a single outlet to hundreds.
Register the QR IDs your bank has issued to your business and outlets.
Activate each QR ID against your PeGePay merchant account.
Use the PeGePay APIs and apps straight away, with payments credited to your own bank account.
PeGePay vs soundboxes and terminals
| Soundbox | Standalone terminal | PeGePay | |
|---|---|---|---|
| Confirms a payment arrived | Yes, by voice | Yes, on its own screen | Yes, in real time |
| Payment tied to a specific order or bill | Typically no | Typically no | Yes, dynamic QR per order |
| Updates your POS or ERP automatically | No | No | Yes, via API and callbacks |
| Works for online checkout and QR codes printed on invoices | No | No | Yes |
| Triggers IoT devices, such as gates and kiosks | No | No | Yes |
| Reconciles by store, terminal and shift | No | Within the device only | Yes |
General comparison. Some bank and vendor devices add features such as card acceptance or their own POS software; check the specific product.
Enhanced APIs
Not raw core bank APIs. Capabilities designed around how merchants actually run their operations.
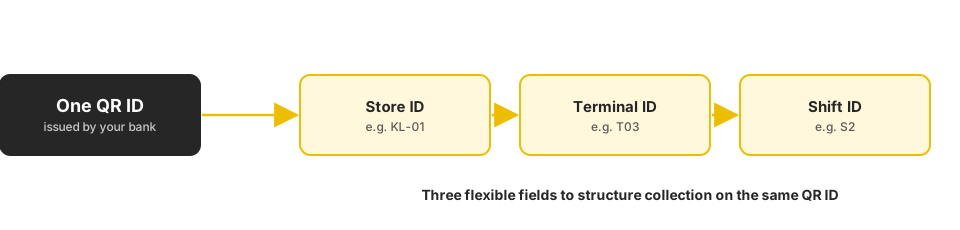
Structure collection systematically with a Store ID, Terminal ID and Shift ID on the same QR ID, with no extra QR IDs to provision.
Generate a QR for each order or bill. Where it meets business needs, PeGePay supports the use of both static and dynamic QR using different channels simultaneously.
Know the moment a payment lands. Banks provide QR payment confirmation reports only daily, while PeGePay keeps a real-time history of every transaction. Access it on demand through the merchant console, the API or a download, for reconciliation, revalidation and reporting. Many companies run staff shifts within a day or close across days, which a bank's daily report cannot support, so they use PeGePay reporting for validation instead.
Update your own systems automatically. Some banks still offer only traditional transaction status polling. That works for a small setup of a dozen or fewer payment points, but across hundreds of POS machines it uses expensive server resources for no good reason, and it makes little sense for dynamic QR codes with a long validity period. Not all callbacks are equal either: most provide only the transaction number. PeGePay callbacks also carry the three structured reference fields (Store ID, Terminal ID and Shift ID), giving merchants high flexibility in updating their backend systems.
We enhance the QR validity period feature so the payable amount can change depending on when the payer opens the live QR payment window. For example, a payer scans a generic QR on a carpark fine slip and pays a flat compound of RM30 within 30 days, or RM300 if payment is made after 30 days.
Detect repeat payments against the same transaction, with clear tracking for refunds.
Depending on the bank your QR ID is provisioned with, you can make both full and partial refunds. Refunds are made immediately against an existing paid transaction, and the money goes back to the payer's bank or e-wallet account, whichever they paid from.
Get alerted when bank callbacks are delayed, which core bank APIs do not provide.
The result
Payments are credited to the merchant's bank account in real time, at a lower MDR than cards, with far less deployment cost and IT effort.
Because we have already integrated with the banks, setup and verification take about two minutes per QR ID. Merchants can start collecting payments straight away, with no integration project to wait for.
Ready-made apps
Messaging commerce
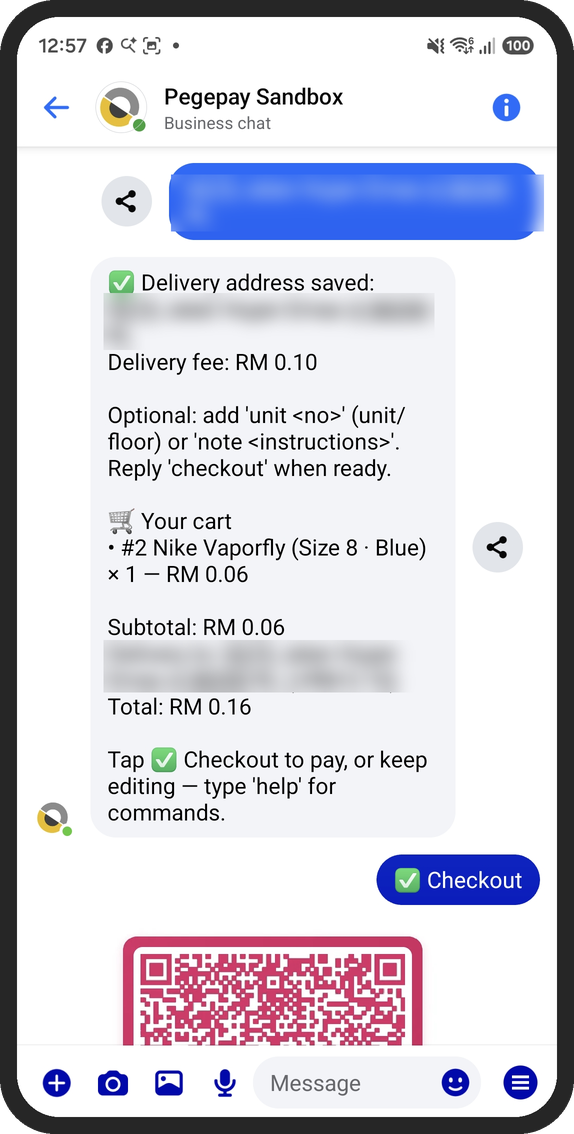
Buyers who message a business on Facebook Messenger, Instagram or Telegram can browse products, get answers to their questions, add products to cart and pay by DuitNow QR, all without leaving the chat. No separate checkout app, and no manual bank transfer screenshots to check.
Connect your Facebook or Instagram page, or your Telegram channel, and sync your product catalogue easily.
Customers browse your products and promotions in the chat, and AI answers their common enquiries around the clock.
Customers select product specifications, add to cart, choose their preferred delivery method, and pay by DuitNow QR inside the chat. Payment is confirmed automatically.
Once an order is paid, book your preferred courier for it from the commerce console.
Payments are credited to the merchant's own bank account through the QR ID their bank assigned, so the messaging commerce bots run on the same DuitNow QR platform described above.
Customer stories
Customer story 01
PeGePay helped this operator introduce DuitNow QR payments across more than 200 carparks, giving motorists a more convenient cashless payment option.
Read the story
Customer story 02
PeGePay helped this laundromat chain eliminate the need for physical payment terminals at new outlets, lower payment processing costs and reduce cash handling.
Read the story
Customer story 03
PeGePay helped this university simplify cross-border tuition payments by enabling parents in China to pay directly via Alipay/WeChat, reducing payment costs and processing times while easing the administrative workload for its finance team.
Read the storyWhy PeGePay
Most payment companies collect your sales money first, take their cut and pay you days later. PeGePay never holds your money. We take the DuitNow QR you already have from your own bank and make it do much more, so every sale goes straight into your own bank account.
PeGePay works alongside: it creates the QR, confirms the payment and updates your POS, ERP/CRM, online store or machine.
DuitNow QR moves money from your customer's bank directly to yours. A payment gateway puts itself in the middle: it collects the money, takes a cut that includes its own markup, and pays you days later. With PeGePay you use the QR ID your own bank gave you, so nobody in the middle holds your money, there is no payout to wait for and no middleman's extra fee. The MDR you pay is your bank's, and it depends on your bank.
On its own, a bank QR is a standee at the counter, a soundbox and a daily report. PeGePay adds what a business needs on that same QR: a QR for each order, automatic updates to your POS and ERP/CRM, refunds, and sales reports by store, terminal and shift. We have already done the connection work with the banks, so setup takes about two minutes per QR ID and there is no integration project.
Payment gateways are built mainly for online checkout and their own proprietary payment terminals. PeGePay covers online checkout too, and also the cashier counter, POS, printed invoices, tap-to-pay, unattended machines and carparks, and selling inside Messenger, Instagram and Telegram. Neither banks nor payment gateways offer all of this in one place.
Three practical results you get once your QR ID is set up on PeGePay.
| Typical payment gateway | PeGePay | |
|---|---|---|
| Where the money goes first | The gateway's account | Your own bank account |
| When you receive it | T+1, T+2 or longer | Real time (bank dependent) |
| MDR on each sale | The bank's MDR plus the gateway's markup, deducted before payout | Bank dependent, and much lower because there is no gateway markup |
| Where it works | Mainly online checkout and proprietary payment terminals | Counter, POS, invoices, online, machines, chat |
| If you change bank | Not applicable; the gateway holds the account | Your integrations stay as they are |
General comparison based on how payment gateways publicly describe their own settlement and fees. Terms vary by provider.
PeGePay is a multi-channel DuitNow QR platform and the flagship product of PeGeBak. It complements your bank's existing channels: you keep your bank's QR IDs and your own bank account, and PeGePay adds the APIs and apps that connect each payment to your business systems.
No. We have already done the integration with the banks. A merchant needs only the QR ID assigned by their bank. There is no bespoke integration project to scope, fund or maintain.
Provision the QR IDs your bank has issued to your business and outlets, activate each one against your PeGePay merchant account, then go live with the APIs and apps. Setup and verification take about two minutes per QR ID.
Payments are credited to your own bank account through the QR ID your bank assigned.
Your integrations survive a change of bank, so your POS, ERP and other connected systems do not need to be rebuilt.
Soundboxes and standalone terminals confirm that a payment arrived, but they do not update your systems, so reconciliation stays manual. PeGePay ties each payment to an order or bill and passes it to your POS, ERP, online checkout or IoT devices automatically. See the comparison table above.
POS, ERP and other enterprise systems, online checkout, QR codes embedded on invoices, and IoT devices such as gates and kiosks, through APIs and callbacks.
Three flexible fields carried on the same QR ID. They let you structure collection by store, terminal and shift without provisioning extra QR IDs, and they drive day-end reconciliation by store, terminal and shift.
PeGePay sends callback latency alerts when bank callbacks are delayed, which core bank APIs do not provide. It also detects repeat payments against the same transaction and tracks refunds clearly.
Yes. NFC tap-to-pay, dynamic QR per bill and time-based amount changes are built for cases such as carparks. See the carpark customer story.
Yes. Buyers who message a business on Facebook Messenger, Instagram or Telegram can browse products, get answers from AI and pay by DuitNow QR within the chat. After payment, merchants book their preferred courier for each paid order from the commerce console. See the messaging commerce section above.
Tell us which bank issued your QR IDs and we will confirm how onboarding works for you.
Pricing depends on your setup and the apps you use. Contact us and we will prepare a quotation for your business.
Use Merchant login at the top right of this page.
Talk to us
Tell us about your business and your bank, and we will walk you through onboarding. We reply from our enterprise team, usually within one business day.
Prefer email? support@pegepay.com
Sign upReady-made apps
| Item | Description | Qty | Amount (RM) |
|---|---|---|---|
| 10 | Maintenance service, Q4 | 1 | 4,200.00 |
| 20 | Spare parts | 3 | 1,350.00 |
| 30 | Delivery | 1 | 150.00 |
| Total due | 5,700.00 | ||
Works with SAP, Salesforce and other enterprise systems through our APIs and callbacks. The invoice shown is an illustrative sample.
Talk to usReady-made apps
32 seconds, with captions. No sound.
A virtual static QR is a fixed DuitNow QR shown on a phone or tablet at your counter. Customers scan it, key in the amount in their own banking or e-wallet app, and pay to your own bank account.
Ready-made apps
Give every merchant you serve DuitNow QR, tap-to-pay and refunds on the POS they already own, with no costly upgrade, and manage every branch, terminal and shift from one QR ID.
| Typical POS integration | PeGePay | |
|---|---|---|
| Customer-facing QR screen | Needs a second screen or a POS upgrade | A low-cost Android phone or tablet becomes the QR display |
| Branches, terminals and shifts | Often a separate QR ID or account for each | One QR ID, with Store ID, Terminal ID and Shift ID on it |
| Tap to pay | A fleet of dedicated terminals to buy and service | NFC tap-to-pay at a fraction of the cost |
| Refunds on QR payments | Often not supported | Built in |
| Payout to the merchant | Next-day wait | Real time (bank dependent) |
| Adding a bank | Another integration project | Integrate once; connected to three banks and growing, with every future bank free |
Set up your POS identification details once, then add as many Store IDs, Terminal IDs and Shift IDs as the business needs. No extra QR IDs to provision, and no new bank paperwork when you open a branch or add a till.
| Store | Terminal | Shift | Payments | Amount (RM) |
|---|---|---|---|---|
| KLCC | Cashier 1 | Morning | 42 | 3,180.50 |
| KLCC | Cashier 1 | Evening | 57 | 4,226.90 |
| KLCC | Cashier 2 | All Day | 61 | 4,870.20 |
| Bangsar | Self-checkout | All Day | 38 | 2,415.00 |
| Penang | Cashier 1 | Night | 24 | 1,764.40 |
| Total, one QR ID | 222 | 16,457.00 | ||
Illustrative sample. Every payment is tied to its store, terminal and shift, so reconciliation with your POS needs no manual matching.
One partnership covers standalone and cloud POS products alike.
Talk to usReady-made apps
20 seconds, with captions. No sound.
A PeGePay QR Touch stand holds an NFC tag. The customer taps their phone on it and the payment page opens straight away, ready to pay by DuitNow QR to your own bank account.
The video shows a laundromat washing machine example.
Talk to usReady-made apps
37 seconds, with captions. No sound. Shown on a Shopify demo store.
Add DuitNow QR as a payment option in your online store. Shoppers pay from their own banking or e-wallet app, and the money goes straight to your own bank account.
The video shows a Shopify store. The phone shown is an illustrative mockup of a banking app.
Talk to us